All You Need To Know About Pak
Have you ever wondered why Pakistani cuisine is winning hearts across Canada? It’s not just the rich…
Latest Updates
September 9, 2026
September 9, 2026
Guides & Resources
Have you ever wondered why Pakistani cuisine is winning hearts across Canada? It’s not just the rich…
What if your next favorite comfort food came from across the globe—but felt like home? Middle Eastern…
For many Muslim consumers, navigating the snack aisle or the pharmacy can feel like a mission in…
What is Eid al-Adha? The Festival of Sacrifice and Devotion While Eid al-Fitr marks the end of…
August 12, 2026 | Last Update September 4, 2026 11:37 pm
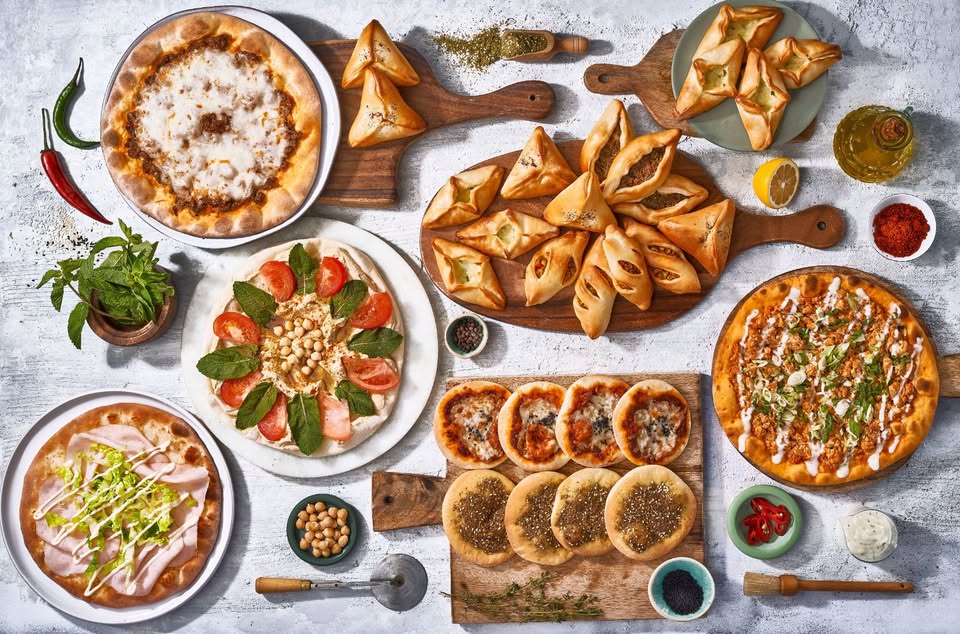
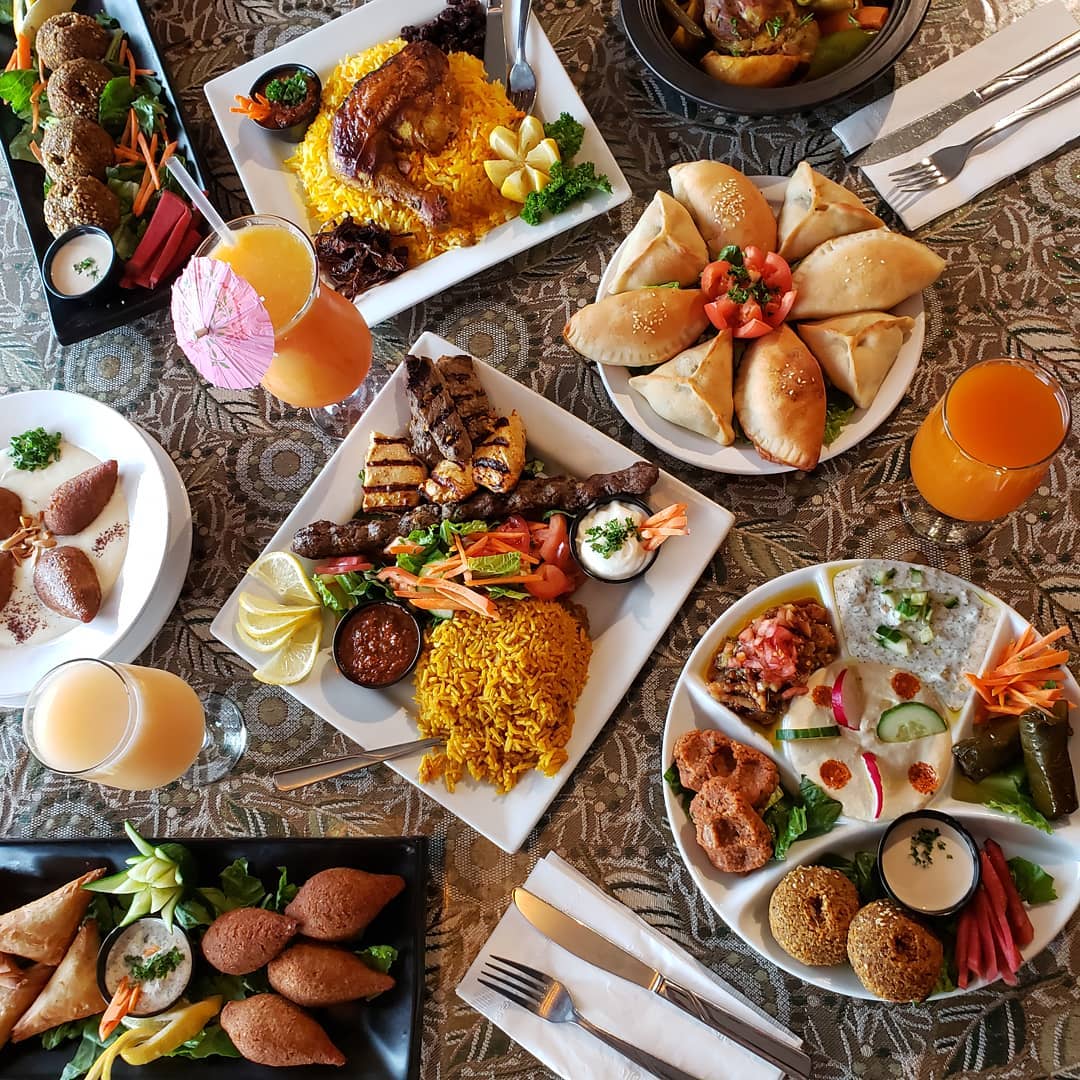
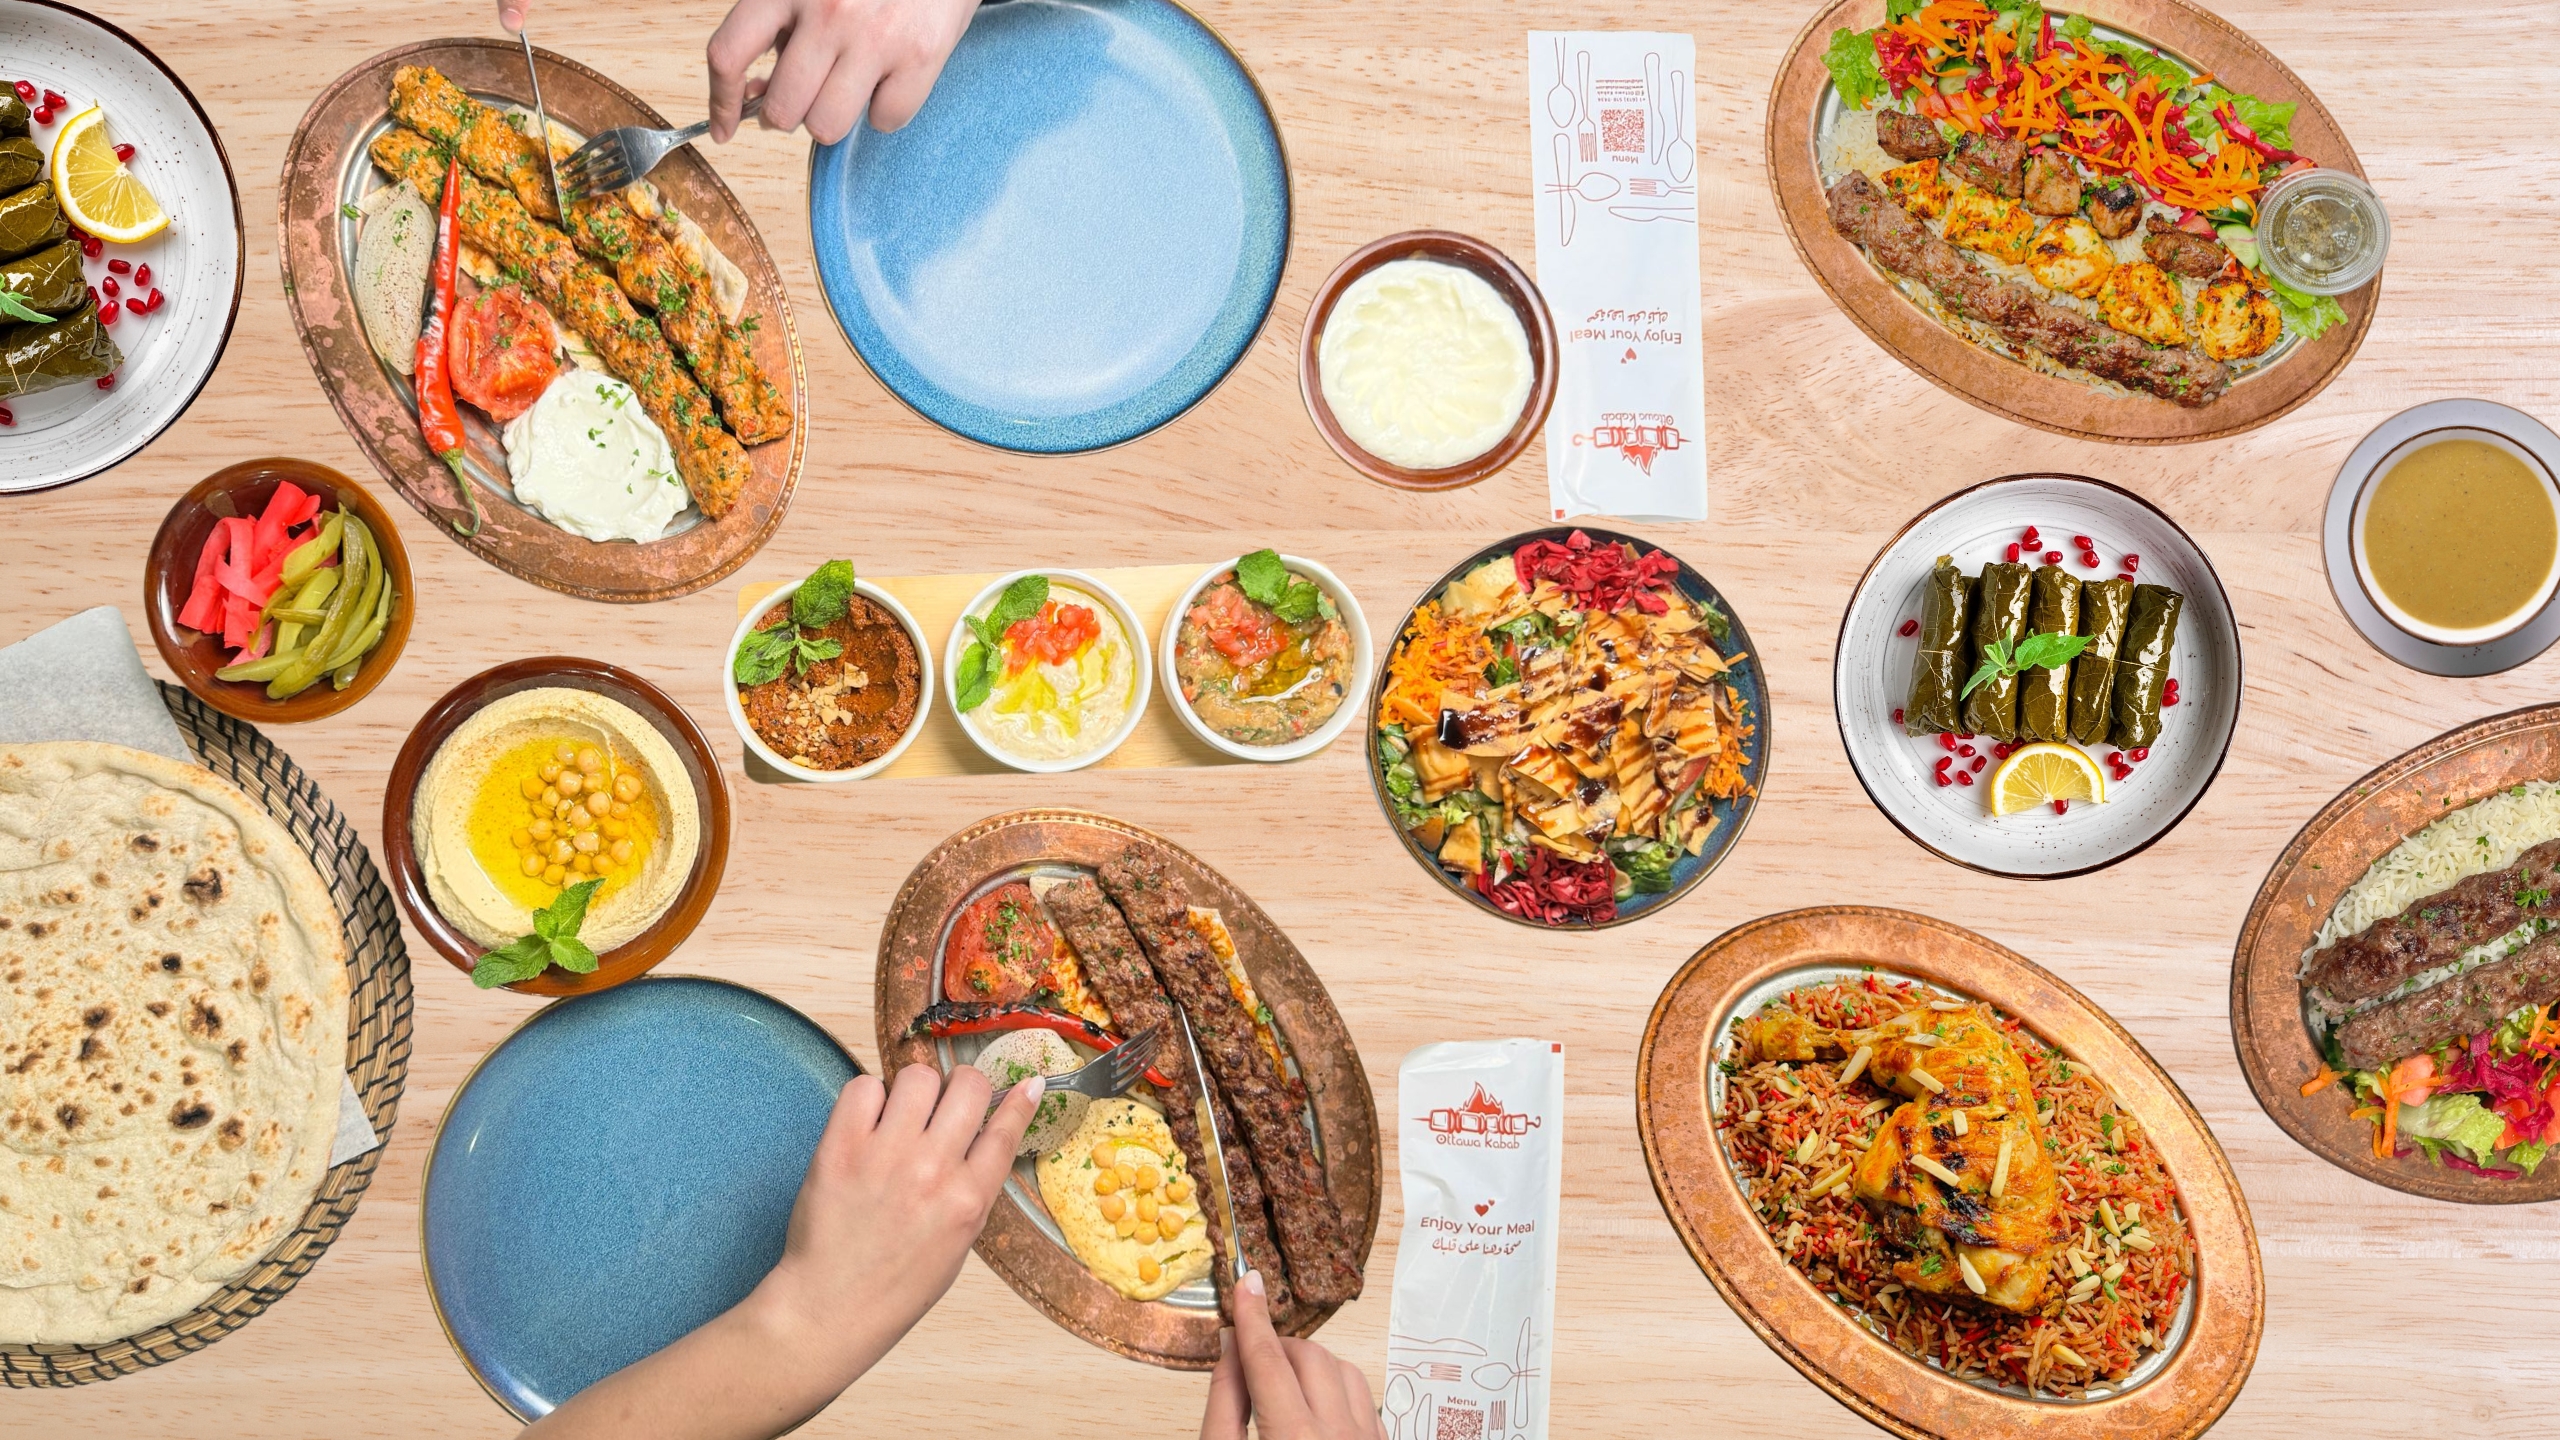
A Middle Eastern Legend bringing authentic flavors to your table
Investing is not automatically haram just because money may grow. In Islamic finance, the key distinction is how the return is earned. Owning a share of a permissible business is fundamentally different from lending money at interest. The challenge is that modern companies, ETFs and investment accounts can mix permissible business activity with debt, interest income and industries Muslims may want to avoid.
A stock represents ownership in a company. If the company’s activities and finances pass a recognized Shariah screen, that ownership can be considered permissible by the scholars or standards applying that screen.
Conventional bonds and many interest-bearing products generate returns primarily from lending money at interest, which is why they are generally excluded from Shariah-compliant portfolios.
There is no single one-line test. Shariah-compliant investing normally combines business-activity screening with financial screening. Standards can differ in methodology, which is one reason two screening apps may occasionally classify the same stock differently.
A company can sell a permissible product and still carry significant interest-bearing debt or earn non-permissible income. Shariah screening standards therefore apply financial ratios and income tests in addition to checking the business itself.
Some Shariah methodologies permit investment in a company that passes the required screens even if a small portion of its income is non-permissible. A purification calculation estimates the portion of dividends or income that should be given away rather than kept. Zakat is a separate religious obligation, and some halal-investing platforms provide calculators to help investors estimate it.
For Canadian Muslims who want a more hands-off approach, Manzil is one of the first places worth researching. Its investment offering is provided through Corex Financial, which Manzil identifies as a registered Portfolio Manager across Canada and an Investment Fund Manager in select provinces and territories.
What about the new Manzil Trading platform? Manzil also has a self-directed Shariah-screened stock-trading platform with AAOIFI screening, Zakat and purification tools. However, its current trading availability page does not list Canada among the supported countries yet. Canadian investors should verify availability before assuming the trading account can be opened here; Manzil’s Canadian managed portfolios through Corex are a separate offering.
A Canadian portfolio-management firm dedicated to Shariah-compliant investing. It says it manages portfolios according to AAOIFI rules and currently serves clients in several provinces including Ontario, Alberta, British Columbia and Quebec.
Zoya is primarily a halal-investing research and screening platform rather than a Canadian portfolio manager. It screens stocks and ETFs, tracks compliance changes, includes Zakat and purification tools, and has an integration with Questrade for Canadian self-directed investors.
Musaffa describes itself as a global halal-investing platform for Muslim investors, with stock and ETF screening, portfolio tools and managed solutions in jurisdictions where those services are permitted. Canadian users can access its research app, but investment services should be checked for current Canadian availability.
| Route | What it is | Best for | Your role |
|---|---|---|---|
| Manzil / Corex | Muslim-focused managed portfolios in Canada | Investors who want professional management plus Shariah oversight | Choose goals and risk level; manager handles portfolio construction |
| ShariaPortfolio Canada | Dedicated Shariah-compliant portfolio management | Investors who want a Muslim-focused advisory relationship | Work with the manager on objectives and account structure |
| Zoya + brokerage | Screening and research layered onto self-directed investing | DIY investors who want detailed compliance research | You choose, trade and monitor holdings |
| Musaffa | Halal screening, research and portfolio tools | Investors comparing individual stocks and ETFs | Verify service availability and manage decisions yourself unless using an eligible managed service |
| Wealthsimple | Mainstream platform with a halal managed portfolio and Shariah-screened ETF | Investors who prefer a familiar Canadian digital platform | Use the halal-specific product rather than assuming every product on the platform is Shariah-compliant |
There are mainstream Canadian options, but they are a smaller part of this guide because the goal here is to highlight institutions and tools built specifically around Muslim investors. Wealthsimple, for example, offers a managed halal portfolio and the Wealthsimple Shariah World Equity Index ETF (WSHR). CIBC Wood Gundy also has advisors who specifically market Shariah-compliant investment guidance, including Dr. Khaled Sultan’s practice.
These can be useful options, but a halal product offered inside a conventional institution does not make every account, ETF, cash feature or investment on that platform halal. Read the product-level methodology. For self-directed accounts, also pay attention to margin borrowing and interest paid or charged on cash balances.
If homeownership is your next goal, read how halal mortgages and home financing work in Canada. For the bigger picture, see The Rise of Halal-Conscious Consumers in Canada.
This article is educational and is not a fatwa or individualized investment, tax or legal advice. Investment values can rise or fall, and Shariah opinions and screening methodologies can differ. Verify the current product, fees, registration status and Shariah methodology before investing.
Middle Eastern Restaurants
Turkish Restaurants
Afghan Restaurants
Fully halal Ottawa pizza and bakery offering pizzas, Afghan breads, qabili palaw, tandoori chicken and family specials.